
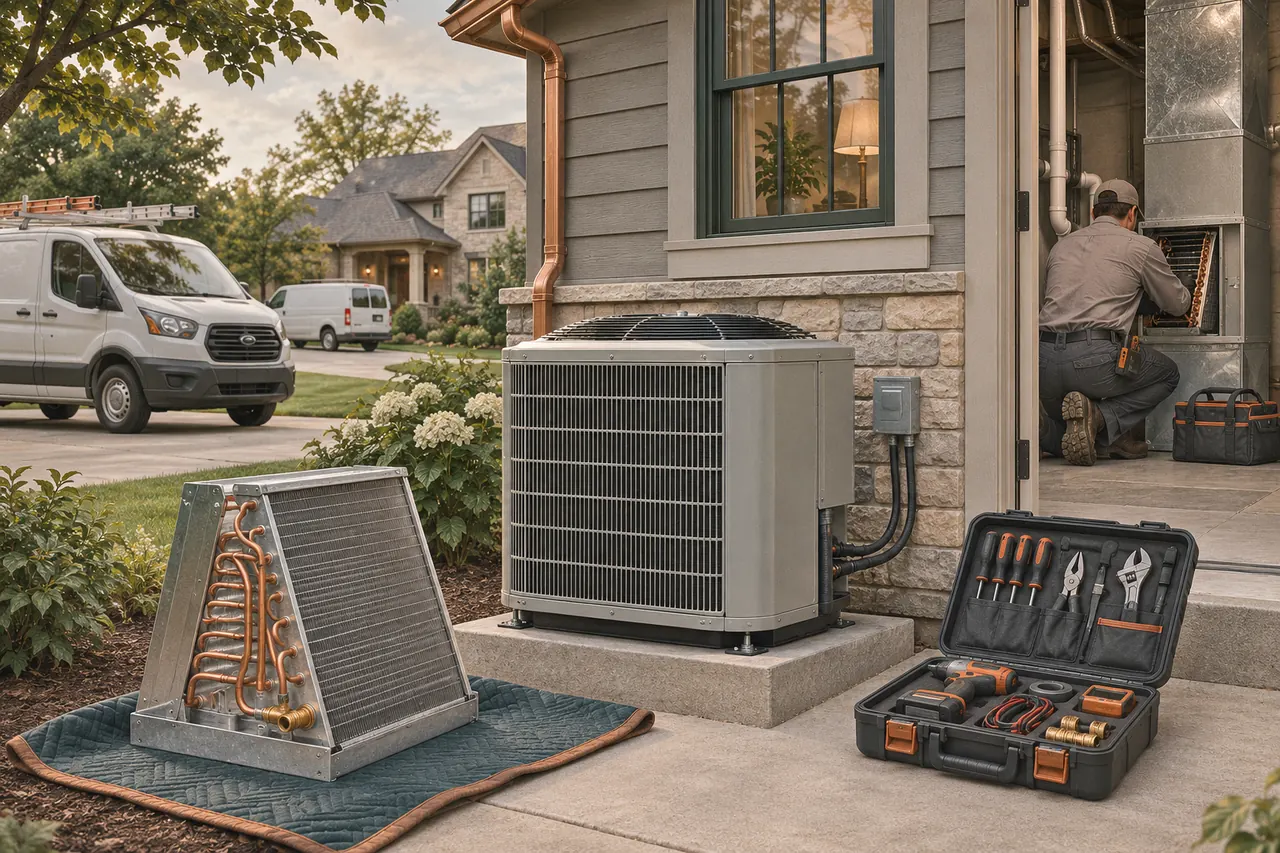
Which warranty actually covers an installation callback?
Start with the document the customer received when the system was installed. A manufacturer may cover an eligible component, the installing contractor may have promised labor and a third party may administer additional coverage. These promises can start on different dates, run for different periods and pay different parties. Your purchase agreement needs to address each exposure the shop actually carries.
Take a customer whose compressor fails shortly after your closing. The homeowner has an installation invoice saying the shop will stand behind its work. The equipment has a manufacturer’s limited warranty. The homeowner also remembers someone mentioning extended protection. Before you price this obligation, retrieve the model and serial number, registration, original proposal, equipment certificate and any extended-service enrollment. What the salesperson recalls is a starting point for finding the record.
Distinguish the relationship with the homeowner from the economic agreement between seller and buyer. You can negotiate who pays the visitor’s labor and who receives a manufacturer reimbursement. Whether a particular customer has enforceable rights depends on the terms, transaction and applicable law. Have counsel review that question before a new dispatcher tells someone that a sale ended the coverage they paid for.
What belongs on the open-installation schedule?
Build an equipment-level schedule of jobs whose labor promise or third-party coverage could still produce work. Include written exceptions, unresolved punch-list items and claims already submitted. Use installation and acceptance records for the beginning of coverage where the applicable agreement calls for them. An invoice date is easy to export but may represent a deposit.
| Obligation | Source record | What to confirm before closing |
|---|---|---|
| Manufacturer part | Certificate, serial number, registration and distributor record | Eligible part, covered period and claims route |
| Installer labor | Signed proposal and applicable customer terms | Remaining period, promised labor and exclusions |
| Extended service | Enrollment, administrator agreement and remittances | Covered work, provider eligibility and available reimbursement |
| Known return visit | Dispatch notes and open work order | Cause, appointment, expected cost and person accountable |
Inspect jobs from each sales channel. A residential salesperson may have offered longer labor coverage as a closing concession. A builder may have negotiated separate punch-list obligations across an entire subdivision. A commercial customer may hold funds until commissioning is complete. Grouping all three under the equipment manufacturer would miss the contractual promise that drives your field cost.
If the source system contains thousands of jobs, begin with the standard agreement versions and the dates when the shop changed them. Identify which salesperson or branch could offer exceptions and request the exception list, then test individual proposals. Keep a category for files with missing terms. Pricing all unknown records as zero simply transfers a documentation problem into your buyer’s opening cash forecast.
How do you estimate the unfunded field cost?
Use the shop’s history to connect the number of covered installations with the frequency and net cost of return work. Estimate different cohorts separately when age, model, installation team or terms affect the outcome. Reconcile your estimate to actual warranty visits, including calls the dispatcher marked as courtesy service.
- Select a past installation cohort with a full period of observable claims.
- Find its return visits using customer, address, equipment identifiers and technician notes.
- Sum paid field time, travel, materials, freight and other costs the shop incurred.
- Subtract actual eligible reimbursements and preserve the time it took to collect them.
- Apply a comparable experience rate to the remaining exposure, then add material known claims separately.
Consider an illustrative block of 300 installations with comparable coverage time remaining. If internal histories suggest six percent will require one unpaid visit and the expected net field cost is $250, the modeled exposure is $4,500. That calculation assumes comparable time at risk and one claim per affected unit. It excludes two known major failures that the service manager has already scheduled. If you price those two jobs individually, remove the overlapping exposure from the general estimate.
The inputs matter more than the neat arithmetic. A new equipment line with a difficult commissioning process may have a different return pattern from the units in your historical cohort. A technician who now drives farther may cost more per visit. A distributor may credit the returned part after inspection while the shop must pay the technician next Friday. Show the timing of recovery in addition to the expected net cost.
Check whether the P&L already reflects recurring warranty labor at a representative level. Earnings may already include ordinary callbacks on the installations driving current sales. A separate closing adjustment for a specific inherited obligation can still make sense, but recording the same expense in normalized earnings, the working-capital calculation and a special holdback can charge for it repeatedly. Reconcile the treatment with the working-capital guide and the agreed accounting definitions.
How can the parties allocate old promises at closing?
Choose a structure that makes the customer service path workable and the financial obligation measurable. The buyer might assume a defined schedule for an agreed adjustment. The seller might retain specified costs and reimburse the operating company. Known large claims might have their own completion arrangement. Each structure needs a real person who can authorize a truck roll.
If you are selling, state precisely which installations and promises you are prepared to fund. Explain which employees can attest to exceptions after your exit and where the buyer will find the original documents. If you retain costs, negotiate the labor rate, travel charge, materials markup, documentation and time to dispute a charge. Your net proceeds calculation should distinguish cash released at close from money reserved against future work.
If you are buying, test the arrangement on a cold-weather weekend. A homeowner calls with no heat after an installation completed by the seller. The outgoing owner cannot be reached. Can your on-call manager authorize diagnosis? Who pays if the cause turns out to be unrelated to installation? How do you handle a needed replacement part that requires advance authorization? Walk through the case with the person who will actually receive the call.
Avoid placing every future disagreement in a shared inbox with no deadlines. Put one owner on the seller side and one on the buyer side. List what evidence closes a claim, when invoices can be batched and when any remaining holdback is reviewed. An escrow amount by itself does little good if neither party can agree whether a second visit belongs to the original defect.
What should dispatch do when the first old customer calls?
Give dispatch one short process that starts with customer service and ends with a documented financial decision. Ask for the service address, installation date, equipment details and description of the problem. Pull the original proposal before making a coverage promise. If an urgent condition requires immediate escalation, follow the shop’s existing service policy and record who authorized the response.
Use the ownership transition worksheet to assign access to old proposals, serial-number histories, distributor claims and past service notes. If the seller’s email contains an exception, capture the relevant business record securely with permission before the account is retired. A new manager needs a retrievable job file, and an outgoing owner needs a defensible record if asked to reimburse a visit months later.
At the first accounting review, match the dispatch work orders to technician time, returned parts, customer charges and third-party credits. Keep a claim open until the remaining financial step is assigned. A completed repair can still have an outstanding manufacturer claim. Conversely, a posted part credit does not show that the homeowner’s system is running or that the shop recovered labor.
A final drill can expose gaps cheaply. Pick one job on the old system, one recent job still under the installer’s promise and one job with third-party coverage. Ask the incoming dispatcher to find each file and route a hypothetical call without relying on the departing owner’s memory. Record where they had to stop and correct those gaps before the final transfer of records.
Revisit the reserve once actual claims accumulate. Compare the number of covered installations remaining, frequency of calls, time per trip and reimbursements received with the opening assumptions. Document whether the difference reflects unusually severe weather, missed registrations, a product issue or an inaccurate history. Your valuation records should let both sides explain the movement in specific jobs and dollars when the remaining funds are released.
Review rejected claims alongside reimbursements. A distributor may have denied a returned component because the shop sent it after a deadline or omitted its original serial tag. A service company may have repaired a unit successfully but never completed the administrator’s claim form. Those are different problems. For the first, your incoming parts manager needs instructions on preserving and returning equipment. For the second, your office needs a person responsible for monitoring claim submissions and matching credits when they arrive.
If the seller offers to retain the entire exposure, discuss what happens if they retire out of state, close their old office or change accountants. Keep an agreed copy of the records and give both parties a working method for exchanging notices. Test the arrangement with one representative claim before you remove the old staff from the workflow. A seller who can verify a charge promptly and a buyer who can explain it clearly are more likely to resolve routine repairs without involving transaction counsel.
Where can you go next?
What else should you know?
Does the manufacturer normally pay all of my technician’s time?
Read the applicable warranty certificate and any separate labor agreement for the installed model. Parts eligibility, registration, travel, diagnosis, refrigerant and labor reimbursement can follow different rules. Match a previously paid claim to the manufacturer’s remittance before treating any part of the shop’s service cost as recoverable.
How should a buyer handle jobs installed just before closing?
Schedule the installation date, open punch items, remaining coverage and any final payment still due. Inspect recent callbacks on comparable jobs and identify who will complete unfinished work. The buyer and seller should agree how those calls will be classified, authorized and paid, and tell dispatch who can decide a disputed case.
Can I use a percentage of sales to set the warranty reserve?
A historical percentage can be a useful cross-check once you establish which costs and sales it includes. Build the estimate from covered installations, remaining time, claim frequency and your expected unreimbursed cost per visit. Compare that result with the general ledger, especially if the shop recently changed equipment or warranty terms.
Who should the homeowner call if the seller keeps the financial responsibility?
Give the homeowner one clear service contact and provide that contact with the records needed to assess coverage. The parties can arrange a separate reimbursement process between themselves. Document emergency authority, evidence required for a claim, billing deadlines and the person who escalates a disagreement without leaving the customer waiting.
Which sources informed this page?
- HVAC warranty and registration · Trane, November 21, 2026
- Warranty registration and coverage · Carrier, November 21, 2026
- Consumer guidance on warranties · Federal Trade Commission, November 21, 2026